Preventing Cybercrime: Essential Steps
Cybercrime led to losses of nearly $21 billion last year. Kurt Knutsson highlighted increasing AI scams, breaking down FBI data that showed investment fraud alone cost victims $8.65 billion. To address this, Knutsson offers a free class on protecting finances and securing accounts.
Understanding Identity Theft
Many associate identity theft with unauthorized access to existing bank accounts or credit cards. However, a different kind of threat involves criminals using personal data like names, Social Security numbers, and birthdates to open new accounts in your name. Such instances of new-account fraud rose by 31% in 2025, affecting 5.4 million victims, according to Javelin Strategy & Research.
Identifying New-Account Fraud
New-account fraud can be elusive, as criminals may open accounts that you don’t typically monitor. Notifications might only appear when you’re contacted by debt collectors or through unexpected mail. Yet, there are preventive measures to catch these signs before they escalate.
Potential Indicators
- Unexpected mail for accounts you didn’t open.
- Debt collector calls about unknown debts.
- Unfamiliar entries on credit reports.
Ways to Protect Yourself
Fast detection is crucial. Here are steps to identify and mitigate harm from new-account fraud.
Steps for Immediate Action
- Check Credit Reports: Visit AnnualCreditReport.com to review reports from Equifax, Experian, and TransUnion. Look for any anomalies.
- Identify Unrecognized Entries: Pay close attention to anything unfamiliar on your reports.
- Freeze Your Credit: A freeze makes opening new accounts in your name challenging. You need to contact each credit bureau separately.
- Monitor Mail and Emails: Be alert for correspondence about unknown accounts.
- Setup Alerts: Use available tools from banks and card companies for monitoring transactions and activities.
Dealing with Fraudulent Accounts
If you discover fraudulent activity, quick action is needed. Here are the steps to halt fraud and begin rectifying your records:
Fraud Resolution Steps
- Contact Originators: Call the companies where accounts were opened and inform them of the unauthorized activity.
- Report to FTC: Create an Identity Theft Report at IdentityTheft.gov.
- Activate Fraud Alerts: Notify one credit bureau to place a fraud alert. It will inform the other two.
- Dispute Fraudulent Information: Contact credit bureaus showing unrecognized accounts and request corrections.
- Leverage Monitoring Services: Enable alerts with financial institutions for added security.
- Keep Detailed Records: Document all communications and maintain copies for reference.
Implementing Preventive Measures
Regularly checking credit reports is vital for spotting unfamiliar transactions early. Speed in addressing issues can greatly reduce potential damage. Freezing credit when not actively applying for new accounts provides a further layer of protection.
Stay informed and vigilant, visiting sites like CyberGuy.com for reliable advice and identity theft insights. Sign up for newsletters or resources, such as the Ultimate Scam Survival Guide, to stay ahead of potential threats.
 AI Concerns and International Relations: Bill Gates Urges Oversight Amidst Global Summit
 Concerns Rise Over AI Development and Geopolitical Implications
 Impact of E.U. Regulations on Google Search
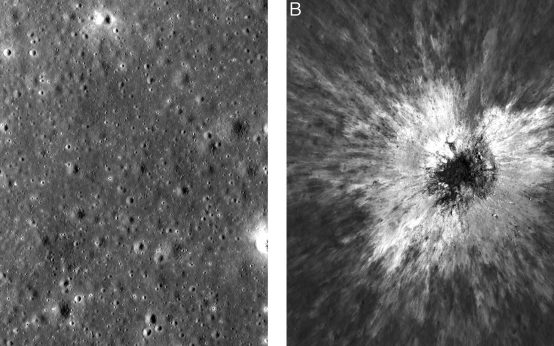 Discovery of Massive Lunar Crater Sheds New Light on Moon’s Surface
 Concerns Rise Over AI Chatbot Safety, Legislation Faces Criticism
 Trump Announces Plan for AI Force and Czar Amid AI Regulation Debate